
Kevin Shilling
5 months ago
Running a hospitality business means looking after more than just your guests. From damage to your property and equipment to accidents involving customers or staff, there are many risks that could affect your business.
Whether you run a hotel, restaurant, guesthouse, takeaway, pub or a business with multiple locations, the insurance you need will depend on your premises, the services you provide and how your business operates.
At Robison & Co, we take the time to understand your business and help you find the right cover to protect your property, people and income.
A guest slipping on a wet floor, a fire damaging your kitchen or a refrigeration failure causing food to spoil could all lead to unexpected costs. Depending on the incident, you could also face a claim or have to close part of your business while repairs take place.
Some risks are less obvious. You might start letting an outside therapist use a treatment room in your hotel, turn a storage area into additional guest accommodation or install a wood fired pizza oven in your restaurant. These changes might seem like part of everyday business, but they could affect your insurance. These changes may not automatically invalidate your insurance. However, if your insurer isn’t aware of them, you could find that your cover doesn’t respond as expected when you need to make a claim.
The impact of an incident can go beyond the immediate damage. If you have to close rooms, cancel bookings or stop serving customers, you could lose income while still having wages, bills and other costs to pay.
Understanding how these risks could affect your business can help you decide what protection you need.
The Hospitality Industry includes a wide range of businesses, from independent venues to large organisations operating across several locations. At Robison & Co, we can help arrange insurance for:
Taking the time to review these details can help you identify gaps in your cover before you need to make a claim.
Your hospitality business may look very different today from when you first arranged your insurance. You might have opened another restaurant, added a spa to your hotel, started hosting weddings or invested in new equipment. But have you checked whether your insurance still reflects those changes?
It’s worth reviewing more than just the policies you have. For example, does your property insurance reflect the current value of your buildings, contents and equipment? If damage forced you to close temporarily, would your Business Interruption cover provide enough financial support while you recover?
There are also activities that may need additional protection. Hosting events, offering leisure facilities or operating across several locations can affect your insurance requirements. It’s important that your insurer understands what your business does and that you know what your policy includes.
Taking the time to review these details can help you identify gaps in your cover before you need to make a claim.
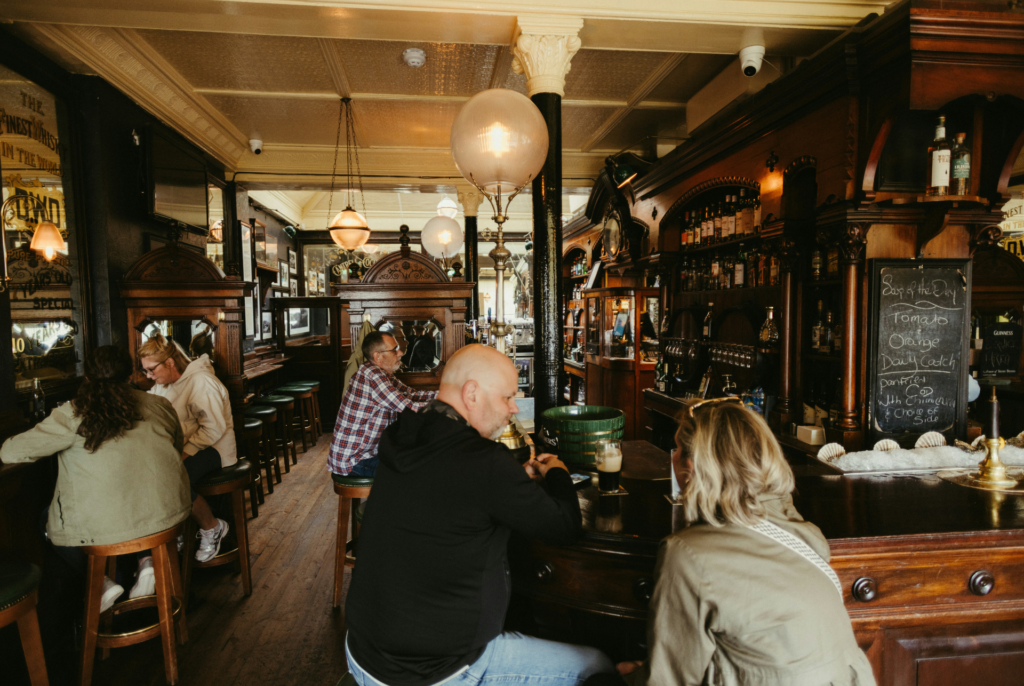
The insurance you need will depend on your premises, employees and the activities you carry out. Some policies may be legally required, while others will depend on the risks involved in running your business. You won’t need a separate policy for every type of cover. Depending on your business and the insurer, several types of insurance can often be combined into one policy, making your insurance easier to manage.
Here are some of the insurance policies you may need to consider:
Rather than arranging separate policies for your property, stock, liability and other business risks, Commercial Combined Insurance can bring several types of cover together under one policy, tailored to the needs of your hospitality business.
If a guest is injured by a faulty chair or a customer becomes ill after eating food you’ve served, your business could face a compensation claim. Public and Products Liability Insurance can help cover the associated legal costs and compensation.
If a storm damages your roof or equipment is stolen, the cost of repairs and replacements could be significant. Buildings Insurance can protect premises you’re responsible for insuring, while Contents Insurance can cover furniture, equipment and stock against insured damage or theft.
If a burst pipe forces your hotel to close several rooms, you could lose income while still having bills and staff costs to pay. Business Interruption Insurance can help cover lost income and certain additional costs while your business recovers from an insured event.
If a chef suffers a serious burn at work or an employee becomes ill because of their work, your business could face a compensation claim. Employers’ Liability Insurance can help cover compensation and legal costs. It’s a legal requirement for most businesses with employees.
Whether you’re organising a wedding, conference or private function, there’s more to consider than the risk of cancellation. Event Insurance can help protect against claims involving injuries or property damage, damage or theft of event equipment, and certain cancellation costs, depending on the cover arranged.
If your pub, bar or restaurant loses its licence to sell alcohol, it could have a significant impact on your income. Loss of Licence Insurance can help protect against certain financial losses if your licence is revoked or renewal is refused for a reason covered by your policy.
If a cyber attack compromises employee records or prevents you from accessing important systems, it could disrupt your business and lead to unexpected costs. Cyber Insurance can provide specialist support, help recover data and cover certain financial losses, depending on your policy.
If your hotel operates guest transport or your catering business uses several delivery vehicles, an accident could lead to repair costs or a compensation claim. Motor Fleet Insurance can cover multiple business vehicles under one policy, depending on the protection arranged.
Other types of cover, including Legal Expenses Insurance, Stock Deterioration Insurance and specialist cover for leisure facilities, may also be worth considering depending on how your business operates. Some of these may already be included within a Commercial Combined policy or wider Business Insurance package, so it’s worth checking what protection you have in place.
If you’re unsure which insurance your business needs, please get in touch. One of our brokers will be happy to discuss your risks and help you understand what cover may be suitable.
Choosing insurance isn’t just about deciding which policies you need. It’s also about understanding what’s included, what isn’t and whether your limits of cover are suitable for your business.
That’s where having a broker can help. At Robison & Co, we’ll review your requirements, discuss the risks associated with your business and approach insurers to find suitable options. We’ll explain the differences between policies, so you can make an informed decision about your cover.
You’ll have a dedicated broker you can speak to when your business changes or you have questions about your insurance. And if you ever need to make a claim, we’ll be there to support you through the process.
Whether you’re opening a new hospitality business, reviewing your existing insurance or simply have questions about your cover, our team is here to help. Get in touch to discuss your insurance needs.
Not all types of hospitality insurance are legally required. However, businesses that employ staff in the UK generally need Employers’ Liability Insurance, which helps cover compensation claims if an employee is injured or becomes ill because of their work.
Other policies, such as Public Liability Insurance, aren’t generally compulsory by law, but may be required by your landlord or under certain contracts. If you or your staff use vehicles for business purposes, you’ll also need to make sure suitable motor insurance is in place.
Yes, it’s possible to insure several premises under one policy, depending on the insurer and how your business operates.
For example, a hotel group or restaurant chain may be able to arrange cover for multiple locations under a Commercial Combined policy. However, each premises will need to be considered individually, including its activities, property values and risks.
It’s important to make sure every location is included and that your policy limits and conditions are suitable for your business.
It can, provided you have the appropriate liability cover in place.
Products Liability Insurance can help with compensation claims and legal costs if someone becomes ill or suffers an allergic reaction because of food or drink your business has supplied, where you’re legally liable.
However, cover will depend on the circumstances of the claim and your policy terms. It’s worth checking that your insurance reflects the food and drink you serve and the activities your business carries out.
Not automatically. Contents Insurance may protect equipment and stock against certain insured events, but mechanical breakdowns and food spoilage aren’t always included.
For example, if a refrigeration unit fails and your food stock becomes unusable, you may need Equipment Breakdown or Stock Deterioration cover to help with the resulting losses.
It’s important to check which incidents are covered, whether any conditions apply and whether your limits reflect the value of the equipment and stock you hold.
It may do, depending on the events you host, what you’ve declared to your insurer and the terms of your policy.
For example, your Public Liability Insurance may cover certain activities at weddings, conferences or private functions. However, events involving external suppliers, entertainment or additional equipment may introduce risks that need to be considered separately.
Event cancellation isn’t necessarily included in your usual business insurance, so it’s worth discussing your arrangements with your broker before hosting an event.
Yes, you should let your broker know about any changes that could affect your business’s risks or insurance requirements.
For example, opening another premises, introducing food deliveries, adding entertainment or expanding your leisure facilities could affect the cover you need.
Your existing policy may still be suitable, but some changes could require additional cover or adjustments to your policy. Checking before making changes can help you avoid unexpected gaps in protection and underinsurance.
If your business relies on selling alcohol, losing your licence could have serious financial consequences. However, standard business insurance doesn’t necessarily cover the resulting loss of income.
Loss of Licence Insurance can help protect against certain financial losses if your licence is revoked, suspended or renewal is refused for a reason covered by the policy.
Not every loss of licence scenario is insured, so it’s important to understand the circumstances your policy covers and any exclusions that apply.
Cyber Insurance can help protect your hospitality business against certain costs and losses caused by cyber attacks, including those affecting booking systems, customer information and payment operations. Cover can also be extended to include money stolen through cybercrime.
Depending on your policy, you may also have access to support designed to help prevent cyber incidents, such as risk assessments, staff training or monitoring services.
If an attack does happen, Cyber Insurance can provide specialist help to investigate what happened, restore your systems, compensate for insured financial losses and manage the consequences, subject to your policy terms.
5 months ago
These guys are simply the best! Their understanding of my requirements, their diligence in getting sensible and rational quotes, and their all round professionalism makes Robinson & Co a top team, the best team. I use Robinson & Co for property insurance, restaurant cover and business travel. If they flew aircraft, I'd fly with them.

7 months ago
I have insured my car with Robisons for over 30 years now, says it all really, top notch service at all times !!!!
8 months ago
Robisons have now been our Insurance Broker for some years and continue to provide and excellent service at all times. Thank you Maria particularly

8 months ago
Danny and the team were fantastic! Friendly, efficient and speedy response times, thank you!

8 months ago
Been a customer for many years, always satisfied with the help, advice and service given during this time.

9 months ago
Great service, easy company to deal with, sorted out our business insurance. Will certainly be using them again.

10 months ago
Simon has been great, managed to get me indemnity insurance and office insurance with better cover and cheaper than I had been offered elsewhere. Smooth, friendly and efficient process. Perfect outcome!

11 months ago
Marie was extremely professional and handled the issue of insuring my late father’s house with tact, sensible questions and an effective result! Thank you

12 months ago
Helped me with business insurance as my current provider were playing silly games. I like the fact Danny could interrogate the policy wording to ensure I was properly protected. Thank you for all your time and help.

1 year ago
Marie made renewing my home insurance surprisingly easy. She was friendly, efficient and completely discreet throughout, which I really appreciated. Nothing was too much trouble and the whole renewal process felt straightforward and stress-free thanks to her help.